Why do solar panels complicate a home sale?
Because "I have solar" describes four completely different legal situations, and sellers routinely do not know which one is on their roof.
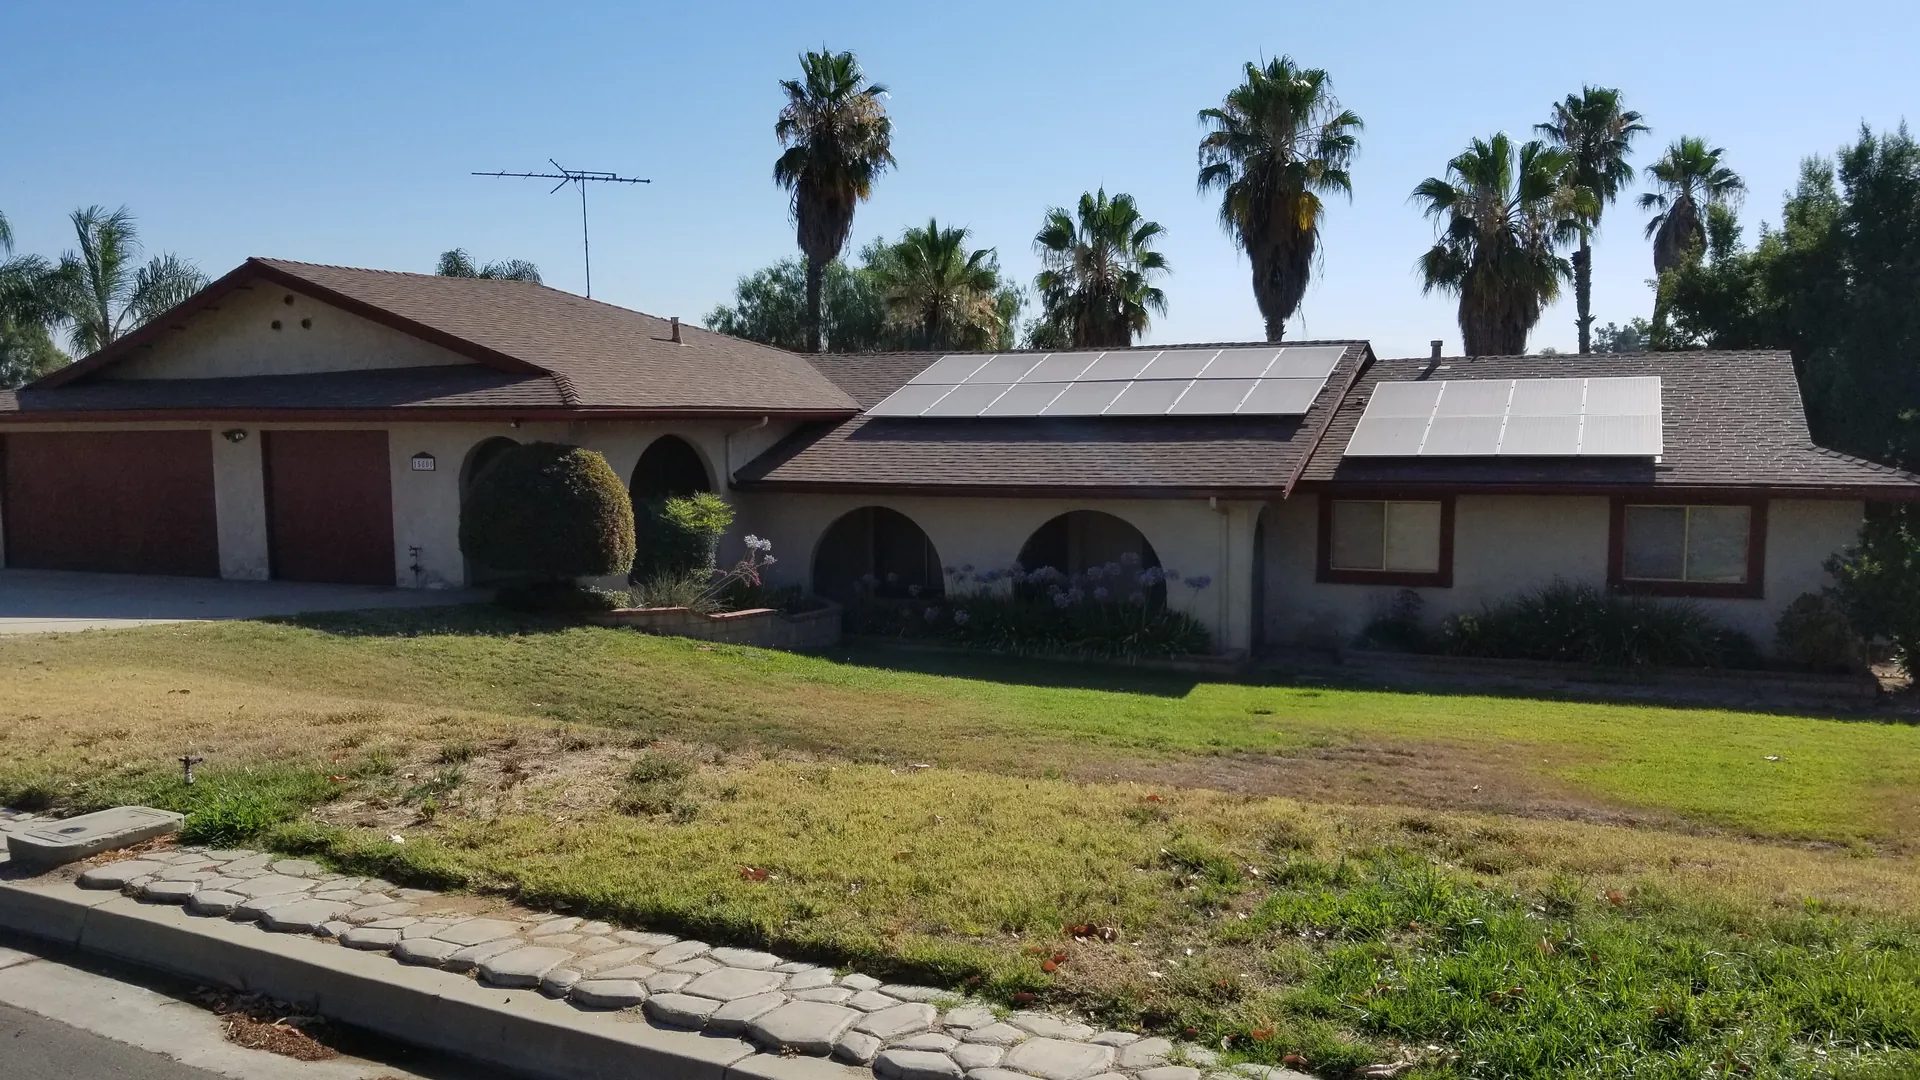
The panels look identical. What is attached to the title is not.
The four arrangements, ranked by how much trouble they cause
Owned outright. You paid cash or you paid off the loan. The panels are a fixture, they convey with the house, they are an asset. This is the easy case and the only one that reliably adds value.
Financed with an unsecured loan. You borrowed to buy the panels, but the lender did not take a lien against the house. You pay it off at close out of proceeds, like any other debt. Slightly annoying, not a problem.
Leased or under a power purchase agreement. You do not own the panels. A third party does, and you are buying the power or renting the equipment. The buyer has to qualify for and assume the agreement, and the solar company has to approve them. That is a separate approval on top of the mortgage approval, it runs on the solar company's timeline, and it has its own credit standard. This is where escrows slip.
PACE. This is the one.
What is a PACE assessment and why does it stop loans?
Property Assessed Clean Energy financing attaches the obligation to the property as an assessment collected on your property tax bill. That is the appeal — no traditional loan qualification, repaid through taxes.
It is also the problem. A tax assessment sits in front of the mortgage in lien priority.
Fannie Mae is direct about it: "The terms of the Fannie Mae/Freddie Mac Uniform Security Instruments prohibit loans that have senior lien status to a mortgage." And on refinances, "Fannie Mae requires that borrowers with sufficient equity pay off the existing PACE obligation as a condition to obtaining a new mortgage loan."
Translate that into a transaction: if your buyer is getting conventional financing and there is a PACE assessment with lien priority on your house, it has to be paid off. Out of your proceeds. At close.
A PACE balance can run tens of thousands of dollars. A seller who has not accounted for it can get to the settlement statement and discover the sale does not clear.
How do I find out which one I have?
Four checks, and you can do all of them this week.
- Pull your property tax bill. A PACE assessment shows as a line item. If it is there, you have PACE, whatever the contractor called it when they sold it to you.
- Pull a title report. Any recorded lien or assessment shows up.
- Find the contract. Lease, PPA, retail installment contract and PACE assessment contract all look different and say what they are on page one.
- Call the provider and ask for a payoff or transfer package in writing. Do this before you list, because the answer takes days and sometimes weeks.
What to do before you list
If you have PACE, get the payoff figure and put it in your net sheet. That number decides your list price, or decides whether now is the right time at all.
If you have a lease or PPA, get the transfer requirements in writing and disclose them up front. A buyer who learns about a twenty-year power purchase agreement in week three of escrow feels misled even when the disclosure was technically delivered. A buyer who knows on day one prices it in and moves on.
If you own the panels, say so, and have the documentation to prove it. "Owned solar" in a listing with nothing behind it makes a careful buyer suspicious.
Does removing the panels help?
Almost never. Removal costs money, leaves roof penetrations, and does not extinguish a PACE assessment — that stays with the property regardless of whether the equipment is still on it.
The honest summary
Solar is not a problem. Unknown solar is a problem. The seller who walks in with the tax bill, the title report, the contract and a written payoff figure has a routine transaction. The seller who says "I think it came with the house" has a three-week detour waiting for them in the middle of escrow.
Find out which one you are before a buyer does.
Sources
Jeff Maas
Broker-Owner · DRE #00981576 · NMLS #246684
Jeff Maas has been a licensed California real estate professional since 1988 and opened National Realty Group in Riverside in 1991. He is the broker-owner of the brokerage and CEO of National One Mortgage Corp, and he founded Escrow One and America's Best Property Management, giving clients real estate, lending, escrow and property management under one roof. Jeff has closed more than 1,000 transactions for buyers, sellers and investors at every price level, and ranks in the top 5% of producers in Southern California by MLS production. He has won National Realty Group's Eagle Award — given to agents producing more than $250,000 in gross income in a year — three years running, and has earned the 1% Award from United Wholesale Mortgage. He teaches real estate at California Baptist University, serves as CFO for Bethel Christian Schools, and is a member of the California Association of REALTORS® and the National Association of REALTORS®. He works with clients across Riverside, San Bernardino, Orange, Los Angeles and San Diego counties.
More from Jeff →This post is general information, not legal, tax, lending or investment advice, and it is not a guarantee of any result. Market figures are accurate as of the date shown and change. National Realty Group is an Equal Housing Opportunity brokerage.